On this page
How long does pre approval last is usually asked a week before an auction, which is late. The standard answer is ninety days with most lenders, though some run to six months and a few are shorter.
The more useful answer is that the expiry date is not the thing most likely to catch you out. Pre approval is conditional for its entire life, and several things can undo it well before it lapses.
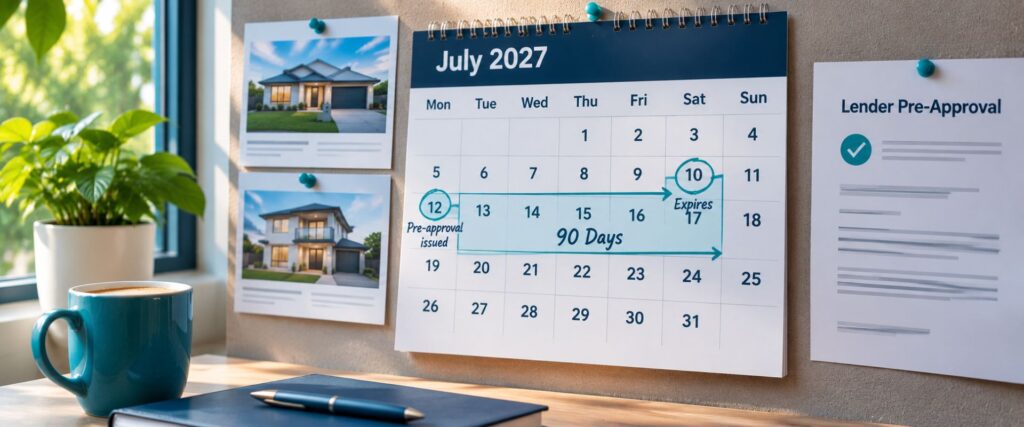
How long does pre approval last? Ninety days is the common position. It is set by the lender rather than by regulation, and that window is long enough to search seriously without the financials going stale.
How long does pre approval last at the longer end? Some lenders issue six month approvals, usually for stronger applications or specific products. Some issue shorter ones.
There is no regulated period, so how long does pre approval last is genuinely a lender by lender question rather than a market rule.
The clock starts from the date of issue, not from when you start looking. A pre approval obtained during a tyre-kicking phase can be most of the way through its life by the time you bid seriously.
That is the practical argument for timing it. Get it when you are ready to buy, not when you are ready to browse.
How long does pre approval last matters less than what it actually is. Pre approval is also called conditional approval, and the second name is the more honest one. It is an indication of what the lender will lend, subject to conditions that have not yet been satisfied.
How long does pre approval last is therefore the wrong worry. Those conditions typically include verifying the documents you supplied, and a valuation of the specific property you end up buying that the lender finds satisfactory. Neither has happened at pre approval stage.
This is why a pre approval is not a guarantee and should never be treated as one, particularly at auction where there is no cooling off period in New South Wales.
The gap between conditional and unconditional is set out in conditional versus unconditional approval, and it is the single most misunderstood step in the process.
How long does pre approval last has an obvious answer and a practical one. The expiry date is the obvious limit. These are the less obvious ones, and they are more common.
A change in your income or employment is the big one, and it ends a pre approval regardless of how long does pre approval last on the paperwork.
Changing jobs, moving from permanent to contract, or a drop in overtime or bonus income all change the assessment the approval was based on.
New debt does the same thing. A car loan, a new credit card, or even an increase to an existing card limit reduces borrowing capacity, because lenders assess the limit rather than the balance.
Rate movements matter too. The Reserve Bank lifted the cash rate to 4.85 per cent on 3 November 2026, the fifth rise of the year. Approvals issued before a rise are assessed on the earlier serviceability assumptions, and the amount may no longer hold.
When the answer to how long does pre approval last runs out, most lenders will extend or reissue it, and in most cases there is no fee for doing so.
What it does require is updated information. Recent payslips, current liability figures and sometimes fresh bank statements, because the lender is reassessing rather than simply stamping the old decision.
That reassessment is where a renewal can come back lower than the original. If rates have risen or your circumstances have shifted, the new figure reflects today rather than three months ago.
| Typical position | What to check | |
|---|---|---|
| Standard validity | 90 days from issue | Confirm the date with your lender, not the broker portal |
| Longer validity | Up to 6 months with some lenders | Often tied to specific products or stronger files |
| Cost to renew | Usually nothing | Some lenders charge a reassessment fee |
| What renewal needs | Updated payslips and liabilities | Treat it as a fresh assessment |
| Risk on renewal | A lower approved amount | Rate rises since issue are the usual cause |
| Credit file impact | Depends on the lender | Ask whether a new enquiry is recorded |
Figures reflect common lender practice as at November 2026 and vary. Confirm the position with the specific lender before relying on it.
Some lenders record a credit enquiry when they issue a pre approval and some do not, depending on whether the assessment is a full application or a system-generated indication.
This matters because enquiries are visible to other lenders and a cluster of them in a short period reads badly. It suggests either shopping around aggressively or being declined repeatedly, and the file does not distinguish between the two.
So the answer to how long does pre approval last has a companion question that is rarely asked: does getting another one cost me anything on the file? Ask before you apply to a second lender.
This is one of the clearer arguments for going through a broker, who can assess which lender fits before an enquiry is lodged rather than after.
However long does pre approval last with your lender, ninety days is not long in a market where you may be outbid several times. Treat the window as a resource rather than a formality.
Get the approval when your search is genuinely active. Keep your financial position still during it, which means no new debt, no job change, no credit limit increases and no large unexplained movements through your accounts.
Tell your broker immediately if anything changes, whatever how long does pre approval last in your case. A change disclosed early can often be worked around. The same change discovered at unconditional stage, after you have exchanged, cannot.
The full sequence from application to settlement is in the home loan application timeline, the documents in the document checklist, and the purchase itself on our Sydney residential property loan broker page.
You can, and many buyers do, but understand the risk. Pre approval is conditional and the lender has not yet valued the property you are bidding on, however long does pre approval last on paper.
There is no cooling off period at auction in New South Wales, so if the valuation comes in low or a condition is not met after you have exchanged, you are committed to a purchase you may not be able to fund.
Talk to your broker about the specific property before auction day.
No. It is an indication based on the information supplied, subject to verification of your documents and a satisfactory valuation of the property. Those conditions are what separate conditional approval from unconditional approval.
Most pre approvals do convert, but the ones that fail tend to fail on the valuation or on something that changed in the applicant’s circumstances between issue and settlement.
It can, depending on the lender. Some record a credit enquiry when issuing a pre approval and others do not. Enquiries are visible to other lenders and several in a short period can read poorly, because the file does not show whether you were shopping around or being declined.
Ask the lender or your broker whether an enquiry will be recorded before you apply, particularly if you are considering more than one.
You can, but it is rarely a good idea. Each application that records a credit enquiry adds to your file, and a cluster of enquiries in a short window can count against you with the lender you eventually choose.
A broker can assess which lenders suit your circumstances before any enquiry is lodged, which achieves the same comparison without the marks on your credit file.
Nothing dramatic. Most lenders will reissue or extend it, usually at no cost, once you supply updated payslips and current liability figures.
Treat it as a fresh assessment rather than a formality, because the amount can come back lower than the original if rates have risen or your circumstances have changed.
Start the renewal before the expiry rather than after it, whatever how long does pre approval last turned out to be in your case.
Get it when your search is genuinely active rather than at the browsing stage.
The clock runs from the date of issue, so an approval obtained months before you are ready to bid can be most of the way through its life by the time it matters, whatever how long does pre approval last with that lender.
Knowing your borrowing capacity early is useful, but it is a different exercise from holding a live conditional approval.
An independent overview of what a broker does, what to ask, and how pre approval fits into the application sequence is in the ASIC Moneysmart guidance on using a mortgage broker. It is worth reading before your first application rather than after it.
Paritosh Wadhwani | Director and Principal Broker, APW Finance
Member of the Finance Brokers Association of Australia (FBAA). Arranging residential, commercial and specialist lending for Sydney clients across a panel of more than 50 lenders.
APW Finance Pty Ltd, 304/20a Lexington Drive, Bella Vista NSW 2153. Email: info@apwfinance.com. Phone: +61 447 959 546.
ACN 620 646 479 | ABN 79 620 646 479
This guide is general information only. It does not take into account your objectives, financial situation or needs, and it is not financial or credit advice. Lending criteria, interest rates, duty thresholds and government schemes change, and every application is subject to lender approval.
Consider whether this information suits your circumstances and seek independent advice before acting. Figures quoted are current at the date below and should be confirmed before you rely on them. Last reviewed: November 2026.
APW Finance Pty Ltd delivers expert lending solutions with personalised service, empowering clients across residential, commercial, and business sectors.