On this page
Capitalise LMI into your home loan and you borrow the insurance premium rather than paying it at settlement. Almost every lender allows it, almost every borrower under a twenty per cent deposit is offered it, and very few are shown what it costs.
It is not a free deferral. The premium joins the loan balance and attracts interest for as long as the loan runs. Whether that is the right call depends on what the cash would otherwise do.
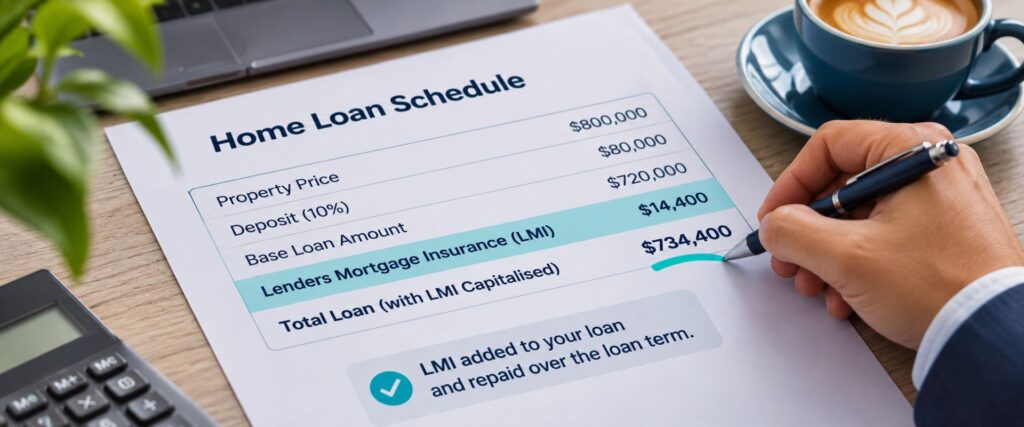
Before you capitalise LMI into your home loan it helps to be clear what the premium is. Lenders mortgage insurance protects the lender, not you, where the loan exceeds eighty per cent of the property value. The premium is a one-off charge, and it is payable at settlement.
When you capitalise LMI into your home loan, the lender adds the premium to the amount borrowed instead of taking it from your funds. You settle with the cash you have rather than the cash you have minus the premium.
That is the whole attraction. For a borrower who has scraped together a deposit, finding another five figures at settlement is often simply not possible, and capitalising removes that obstacle.
What LMI is and when it applies is covered in the LMI explainer, and the premium scale in how much LMI costs.
The premium itself does not change when you capitalise LMI into your home loan. What changes is that you pay interest on it, and over a thirty year loan that interest can approach or exceed the premium.
The arithmetic is the same as any borrowing. A premium carried for the full term at a rate near six per cent roughly doubles in total cost. Carried for five years before you refinance or sell, it costs far less.
That is the question worth asking, and almost nobody asks it: how long will this loan actually run? Most Australian mortgages are refinanced or discharged well inside thirty years, which changes the real cost substantially.
With the cash rate at 4.85 per cent following the Reserve Bank’s decision on 3 November 2026, the carrying cost of a capitalised premium is higher than it has been for most of the last decade.
This is where the decision to capitalise LMI into your home loan gets technical, and where applications fail unexpectedly. The capitalised premium usually counts toward the loan-to-value ratio, which means it can push you past the lender’s cap.
Most lenders cap LMI loans at ninety five per cent. If that cap is expressed inclusive of LMI, then your borrowing before the premium has to sit below ninety five so the premium fits underneath it.
Some lenders allow a higher ceiling inclusive of the premium, which effectively permits borrowing above ninety five per cent of the property value once the insurance is added. Policy varies and it is not always published.
The practical consequence is that a borrower at the edge of a cap may be able to capitalise with one lender and not another, on identical numbers. That is a panel question rather than a maths question.
Neither option is universally better. Whether to capitalise LMI into your home loan depends on whether the cash has a better use, and on how long the loan will run.
| Pay upfront | Capitalise | |
|---|---|---|
| Cash needed at settlement | Deposit plus costs plus the premium | Deposit plus costs only |
| Interest paid on the premium | None | For as long as the loan runs |
| Effect on LVR | None | Usually counts toward the lender cap |
| Effect on repayments | None | Higher, in proportion to the premium |
| Best suited to | Borrowers with cash to spare after settlement | Borrowers whose deposit is the binding constraint |
| Watch for | Leaving yourself no buffer after settlement | Being pushed above the lender LVR cap |
A borrower who would otherwise settle with nothing left is usually better capitalising and keeping a buffer. A borrower with surplus cash and a long intended hold is usually better paying it.
Whether you capitalise LMI into your home loan or pay it, the premium is sometimes partially refundable if the loan is discharged early, typically within the first year or two, and the refund scale drops away quickly after that.
Policies differ by insurer and by lender, some offer no refund at all, and the window is short enough that most borrowers never reach it. It is not a reason to choose one payment method over another.
A more common misunderstanding is that LMI transfers. It does not. Refinance to a new lender while still above eighty per cent and a fresh premium is payable to the new insurer.
That is a real cost of refinancing early at a high LVR, and it belongs in the comparison alongside the rate. Our Sydney no LMI home loan broker page sets out the routes that remove the premium entirely.
Before you decide whether to capitalise LMI into your home loan, it is worth checking whether you have to pay it at all. Several routes remove it entirely.
A profession-based waiver removes LMI for accepted occupations at ninety or ninety five per cent, depending on the lender and the field. The list of professions that get LMI waived sets out who qualifies.
A government guarantee removes it for eligible first home buyers entirely. A family guarantee uses a parent’s equity to bring the effective LVR below eighty per cent, which removes the premium at the cost of placing someone else’s property at risk.
Waiting to reach twenty per cent removes the question of whether to capitalise LMI into your home loan altogether, and in a falling market it is sometimes the right call. The guide to avoiding LMI weighs the four against each other.
Yes. The premium becomes part of the loan balance, so repayments are calculated on the larger amount. The increase is proportional and on a typical premium the increase is modest in monthly terms, which is exactly why borrowers capitalise LMI into your home loan style offers without examining them.
Over a full thirty year term the accumulated interest on that premium can approach the premium itself, so the monthly figure understates what the decision actually costs.
It can, and this is the most common reason an application structured this way is declined. Most lenders cap LMI loans around ninety five per cent and many express that cap inclusive of the capitalised premium, which means your borrowing before the premium has to leave room underneath.
Some lenders allow a higher ceiling inclusive of LMI. Policy varies, is not always published, and is worth checking before you rely on it.
Sometimes, partially, and only within a short window. Refunds are typically available if the loan is discharged within the first year or two, on a scale that reduces quickly, and some lenders and insurers offer no refund at all.
It is rarely enough to influence the decision. Do not count on a refund when weighing whether to pay the premium upfront or add it to the loan.
No. The policy belongs to the original lender and does not move with you. If you refinance while the loan is still above eighty per cent of the property value, a new premium is payable to the new lender’s insurer.
This is a genuine cost of refinancing early at a high LVR and it should sit in the comparison alongside the interest rate, because a lower rate can easily be outweighed by a second premium.
It depends on what the cash would otherwise do and how long the loan will run. If paying upfront would leave you with no buffer after settlement, capitalising is usually the safer choice even though it costs more over time.
If you have surplus cash and intend to hold the loan for many years, paying upfront avoids years of interest on the premium. Whether to capitalise LMI into your home loan has no universally correct answer.
Often, yes. A profession-based waiver removes it for accepted occupations at ninety or ninety five per cent depending on the lender. A government guarantee removes it for eligible first home buyers.
A family guarantee uses a parent’s equity to bring the effective ratio under eighty per cent, so there is nothing to capitalise LMI into your home loan for. Each has conditions, and a family guarantee places someone else’s property at risk.
An independent walk-through of the deposit, the costs at settlement and where mortgage insurance sits among them is in the ASIC Moneysmart buying a house guidance. It is worth reading before you accept a premium as unavoidable, because several routes remove it entirely.
Paritosh Wadhwani | Director and Principal Broker, APW Finance
Member of the Finance Brokers Association of Australia (FBAA). Arranging residential, commercial and specialist lending for Sydney clients across a panel of more than 50 lenders.
APW Finance Pty Ltd, 304/20a Lexington Drive, Bella Vista NSW 2153. Email: info@apwfinance.com. Phone: +61 447 959 546.
ACN 620 646 479 | ABN 79 620 646 479
This guide is general information only. It does not take into account your objectives, financial situation or needs, and it is not financial or credit advice. Lending criteria, interest rates, duty thresholds and government schemes change, and every application is subject to lender approval.
Consider whether this information suits your circumstances and seek independent advice before acting. Figures quoted are current at the date below and should be confirmed before you rely on them. Last reviewed: November 2026.
APW Finance Pty Ltd delivers expert lending solutions with personalised service, empowering clients across residential, commercial, and business sectors.