On this page
Capital gains tax on investment property is being rewritten, and the change is already law. The Treasury Laws Amendment (Tax Reform No. 1) Act 2026 received Royal Assent on 26 June 2026 and the capital gains measures take effect from 1 July 2027.
The fifty per cent discount goes for individuals, trusts and partnerships. Cost base indexation returns in its place, and a minimum tax rate applies to the gain. For anyone holding or buying property, the timing of a sale now matters in a way it has not for twenty five years.
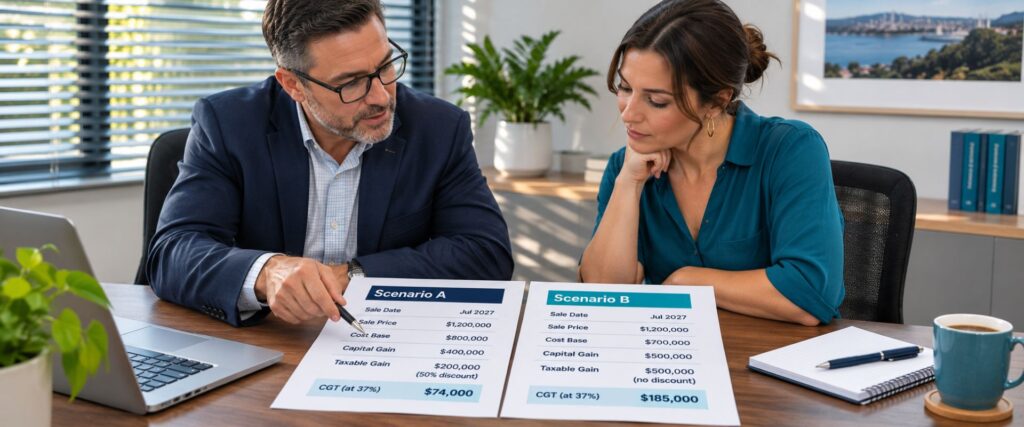
Capital gains tax on investment property changes in one step. From 1 July 2027 the fifty per cent discount is removed for individuals, trusts and partnerships.
It has applied since 1999 to assets held longer than twelve months, and its removal is the largest change to capital gains tax on investment property in a generation.
Two things replace it. The cost base is indexed for inflation, so only the real gain is taxed. And a minimum rate applies to the net capital gain regardless of your marginal rate.
Two things are left alone. Capital gains tax on investment property is being rewritten, but the main residence exemption is unchanged and complying superannuation funds keep their own concessional treatment, which is separate from the individual rules and is not affected in the same way.
This sits alongside the negative gearing change in the same Act, which is covered in the negative gearing explainer. The two measures commence together but work differently.
Indexation is not new. It applied to capital gains tax on investment property before 1999 and the reform brings it back. The purchase cost is lifted by inflation over the holding period, and tax applies only to the gain above that.
The effect on capital gains tax on investment property depends entirely on inflation and holding period, which is why it is not a simple swap. Over a short hold in a low inflation period indexation is worth considerably less than the old fifty per cent discount.
Over a long hold in a high inflation period it can be worth more, because it removes the part of the gain that was never real. With inflation elevated through 2026 and the RBA not expecting it below three per cent until late 2027, that is not a theoretical point.
The index points and the treatment of partial years were still being settled at the time of writing. Work on indicative numbers rather than precise ones until the detail is registered.
A minimum rate of thirty per cent applies to net capital gains from 1 July 2027. If your marginal rate is below that, the minimum applies instead.
This is the part that changes behaviour most. The long standing strategy of timing a sale for a low income year, during parental leave, a career break or early retirement, stops working the way it did.
Income support recipients, including Age Pension holders, are exempt from the minimum. For everyone else, capital gains tax on investment property no longer falls away just because taxable income in the year of sale is low.
Whether holding the asset still makes sense is a separate question from the tax, and whether investment property still stacks up looks at the wider numbers.
Not every asset moves to the new capital gains tax on investment property regime, and the carve-outs are deliberate policy rather than oversight.
New residential dwellings can elect to stay under the fifty per cent discount method. That election is the clearest signal in the reform: the policy is steering investment toward new supply rather than established stock.
Newly built dwellings also sit outside the negative gearing limit in the same Act, so the two measures point the same direction. An investor buying new is treated materially better than one buying established.
The main residence exemption is untouched, and pre-CGT assets acquired before 20 September 1985 keep their exempt status for gains accrued before the commencement date.
Timing is the whole question. Anything sold before 1 July 2027 pays capital gains tax on investment property under the current rules, with the full fifty per cent discount where the asset has been held more than twelve months.
| When you sell | Treatment of the gain | Rate applied |
|---|---|---|
| Before 1 July 2027 | Fifty per cent discount on the whole gain if held over 12 months | Your marginal rate on the discounted gain |
| After 1 July 2027, bought before | Split: the pre-commencement portion keeps the discount, the rest is indexed | Marginal rate on the old portion, 30 per cent minimum on the new |
| After 1 July 2027, bought after | Cost base indexed for inflation, no discount | 30 per cent minimum on the real gain |
| New residential dwelling | May elect the fifty per cent discount method | Marginal rate on the discounted gain |
| Main residence | Exemption unchanged | No capital gains tax |
| Complying super fund | Separate concessional treatment, not changed in the same way | Fund rate |
The table reflects the position as legislated at November 2026. The apportionment detail was still being settled, so treat the middle row as the shape of the rule rather than its final mechanics.
For assets held across the date, the gain is split. The portion that accrued before 1 July 2027 keeps the old treatment and the portion after it uses indexation and the minimum rate.
How that split is calculated was still an exposure draft when this was written, with consultation closed on 21 August 2026 and the formula not yet registered. A market valuation at the commencement date and a time apportionment method have both been canvassed.
That matters practically. The ATO had not published reset guidance or calculators at the time of writing, so anyone planning around the split should expect the detail to firm up before it is needed.
Buying before 1 July 2027 does not lock in the old capital gains tax on investment property rules for the life of the asset, which is the most common misunderstanding we hear. The discount applies to the gain accrued up to commencement, not to the whole gain forever.
What it does do is start the clock on the portion that keeps the old treatment. For a long hold, that early portion can be a meaningful share of the eventual gain.
For capital gains tax on investment property the clearer decision is between new and established. The elections for new dwellings in both the capital gains and negative gearing measures tilt the arithmetic noticeably toward new stock from 2027.
None of this is tax advice, and capital gains tax on investment property interacts with your own circumstances. Structure and deductions are covered in the investment property deductions guide, and the lending side on our Sydney investment property loan broker page.
No. The legislation has passed and received Royal Assent on 26 June 2026, but the capital gains measures do not commence until 1 July 2027. Until then the existing rules apply in full, including the fifty per cent discount on assets held longer than twelve months.
Anything sold and settled before the commencement date pays capital gains tax on investment property under the current regime, which is why timing is being looked at closely by investors holding assets with large accrued gains.
That depends on your own numbers and is a question for your accountant rather than a general answer. Selling before commencement secures the fifty per cent discount on the whole gain.
Holding means the pre-commencement portion keeps the old treatment and the rest moves to indexation and the minimum rate. Transaction costs, the state of the market and your reason for holding all weigh against a purely tax-driven decision.
Income support recipients, including Age Pension holders, are exempt. For everyone else the minimum applies to net capital gains from 1 July 2027, even where the marginal rate is lower.
The practical effect is that realising a gain in a deliberately low income year no longer reduces the tax the way it has done, which removes a strategy many investors have relied on when timing a sale around retirement or a career break.
No. The main residence exemption is not affected by the reform and continues to apply as it does now. The changes target investment assets held by individuals, trusts and partnerships.
If the property has been your main residence for the whole period you owned it, the exemption still applies in full. The partial exemption rules for periods where it was rented out, when capital gains tax on investment property does apply, are also unchanged by this Act.
The gain is split at 1 July 2027. Everything that accrued up to that date keeps the current treatment including the fifty per cent discount, and everything after uses indexation and the minimum rate.
The method for performing that split was still an exposure draft when this was written, with a market valuation at the commencement date and a time apportionment approach both under consideration, so the mechanics may change before they apply.
New residential dwellings can elect to remain under the fifty per cent discount method rather than move to indexation and the minimum rate. Newly built dwellings also sit outside the negative gearing restriction in the same Act.
Together those two carve-outs are a deliberate steer toward new supply, and they change the comparison between a new build and an established property more than most investors have yet priced in.
The current rules, the cost base and how a gain is worked out are set out in the ATO capital gains tax guidance. Check it for the position that applies today, and take advice on your own circumstances before acting on the 2027 changes.
Paritosh Wadhwani | Director and Principal Broker, APW Finance
Member of the Finance Brokers Association of Australia (FBAA). Arranging residential, commercial and specialist lending for Sydney clients across a panel of more than 50 lenders.
APW Finance Pty Ltd, 304/20a Lexington Drive, Bella Vista NSW 2153. Email: info@apwfinance.com. Phone: +61 447 959 546.
ACN 620 646 479 | ABN 79 620 646 479
This guide is general information only. It does not take into account your objectives, financial situation or needs, and it is not financial or credit advice. Lending criteria, interest rates, duty thresholds and government schemes change, and every application is subject to lender approval.
Consider whether this information suits your circumstances and seek independent advice before acting. Figures quoted are current at the date below and should be confirmed before you rely on them. Last reviewed: November 2026.
APW Finance Pty Ltd delivers expert lending solutions with personalised service, empowering clients across residential, commercial, and business sectors.